Last updated: 24 October 2026
Buying a home is often the biggest financial milestone in an individual’s life. The financial load of buying a home can be heavy for a single earner.
This is where Joint Home Ownership steps in as a game-changer.
Joint home ownership allows two or more individuals (usually spouses or family members) to own a property together, offering significant financial and legal advantages:
- Enhanced Loan Eligibility: Combining incomes increases your borrowing capacity, making premium 3 BHK flats in Hyderabad more affordable.
- Double Tax Benefits: Co-owners who are also co-borrowers can separately claim tax deductions up to ₹3.5 Lakhs each (₹2L interest + ₹1.5L principal) per financial year.
- Succession Planning: Ownership structures like “Joint Tenancy” ensure seamless transfer of rights to the surviving owner, while “Tenancy-in-Common” allows distinct shares to be passed to heirs.
Whether you are a young couple eyeing spacious 3 BHK flats in Hyderabad or a family investing in luxury apartments, buying a property jointly isn’t just about sharing a roof, it’s about sharing the financial burden, multiplying tax savings, and securing your family’s future. However, navigating the legal labyrinth of co-ownership requires due diligence. From understanding the difference between “Joint Tenancy” and “Tenancy-in-Common” to mapping out exit strategies in case of disputes, being informed is your best defense.
This guide breaks down everything Hyderabad homebuyers need to know about owning property together in 2026.
Joint Ownership in Hyderabad
Joint ownership is common in Hyderabad, most often between spouses and between parents and children. The driving factor is not only tax optimisation; it is also that combined incomes can make the difference to home loan eligibility.
A common mistake in joint ownership deeds is mismatched shares between the sale deed and the home loan agreement, for example a deed that says 50:50 ownership while the loan is entirely in one person’s name. Align these documents before the registration appointment to avoid delays.
Types of Joint Ownership Structures in India
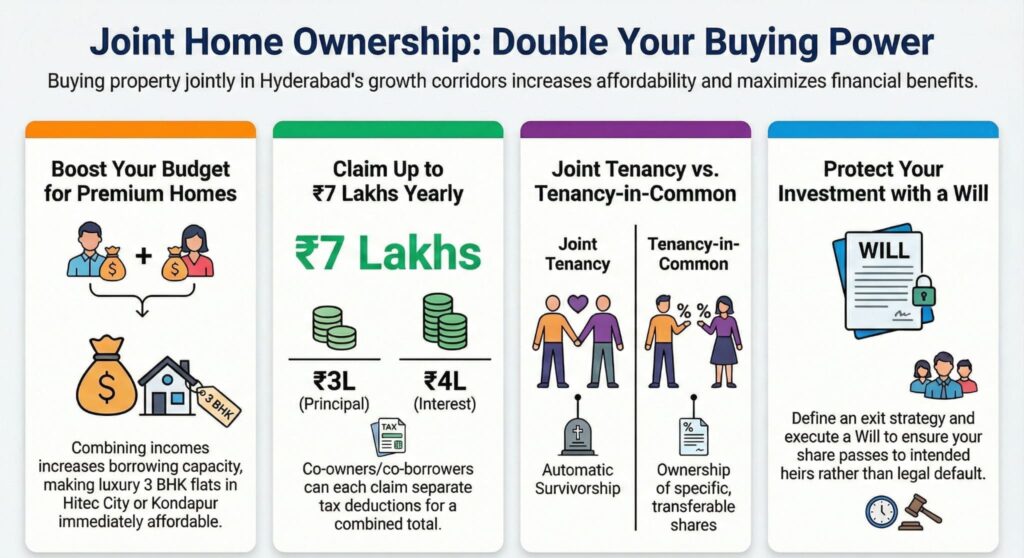
When you sign that sale deed, you aren’t just buying a home; you are defining a legal relationship. In India, joint ownership typically falls into two categories, and choosing the wrong one can lead to severe inheritance complications later.
A. Joint Tenancy (Right of Survivorship)
This is the most common structure for married couples.
- The Rule: In Joint Tenancy, the concept of “Right of Survivorship” applies. If one co-owner passes away, their share automatically transfers to the surviving co-owner, regardless of what a Will might say.
- Ownership Share: Usually, this implies a 50-50 ownership split, though the deed should explicitly state this.
- Best For: Spouses who want to ensure the surviving partner inherits the home without legal hassles.
B. Tenancy-in-Common
This is often preferred by siblings, business partners, or friends buying investment properties together.
- The Rule: Each co-owner holds a specific, distinct share of the property (e.g., Owner A holds 60%, Owner B holds 40%).
- Inheritance: Upon the death of one owner, their share does not go to the other co-owner. Instead, it passes to the deceased owner’s legal heirs as per their Will or succession laws.
- Best For: Investors pooling money for flats for sale in Kondapur or siblings who want to leave their share to their own children.
Pro Tip: Your sale deed must explicitly state the type of ownership. If the deed is silent, Indian courts typically presume “Tenancy-in-Common,” which can be disastrous for a surviving spouse if other legal heirs stake a claim.
A Common Friction Point
A common friction point is the exit strategy. Couples rarely plan for what happens if one party wants to sell. We recommend that all joint buyers execute a co-ownership agreement specifying sale triggers, buyout terms, and dispute resolution before completing registration at the Sub-Registrar’s office.
, Auro Realty Team | Our Editorial Standards
Home Loan Eligibility & EMI Sharing for Co-Owners
One of the primary triggers for joint ownership is the ability to afford a better home. If you have your heart set on luxury apartments in West Hyderabad but your individual salary only qualifies you for a budget home, a joint loan bridges that gap.
Boosting Loan Eligibility
When you apply for a home loan with a co-applicant (spouse, parent, or sibling), the bank considers your combined income.
- Example: If your salary qualifies you for a ₹50 Lakh loan, and your spouse qualifies for ₹40 Lakhs, together you can secure a loan of ₹90 Lakhs.
- Result: This allows you to upgrade from a compact 2 BHK to expansive 3 BHK flats in Hyderabad prime locations immediately, rather than waiting years to save up.
Structuring the EMI Burden
While the bank holds both applicants equally liable for repayment, you can decide how to split the EMI servicing internally.
- Income Ratio Split: Many couples split the EMI in proportion to their salaries (e.g., 60:40). This helps in maximizing tax benefits for the higher earner (more on this below).
- Bank’s Perspective: Remember, even if you agree to pay 50% each, if one defaults, the bank will come after the other for the full outstanding amount.
Tax Benefits Available to Each Co-Owner
This is the financial “sweet spot” of joint ownership. Under the Income Tax Act, tax benefits are not capped per property, but per owner, provided they are also co-borrowers.
Double the Deduction
If you and your spouse are co-owners and co-borrowers, you can both claim deductions separately:
- Principal Repayment (Section 80C): Each can claim up to ₹1.5 Lakhs.
- Combined Benefit: ₹3 Lakhs.
- Interest Payment (Section 24b): Each can claim up to ₹2 Lakhs (for self-occupied property).
- Combined Benefit: ₹4 Lakhs.
The ₹7 Lakh Advantage
For a high-value property, say, one of the premium flats for sale in Kondapur costing ₹1.5 Cr, the annual interest burden in the initial years will easily exceed ₹8-9 Lakhs. A single applicant would max out their ₹2 Lakh limit and lose the rest.
- Jointly: A couple can claim a total of ₹7 Lakhs (₹3L Principal + ₹4L Interest) in deductions annually, significantly reducing the household tax liability.
Crucial Requirement: To claim these benefits, you must be a Co-Owner of the property AND a Co-Borrower on the loan. Being just a “loan guarantor” or just a “name on the deed” without paying EMIs disqualifies you from tax breaks.
Legal Risks, Exit Clauses & Dispute Scenarios
Joint ownership is fantastic when relationships are smooth, but real estate assets are illiquid, making disputes messy. What happens in the case of divorce, estrangement, or insolvency?
The “Exit Strategy” Clause
Before registering the property, co-owners (especially non-spouses) should have a legal agreement outlining an exit strategy.
- Right of First Refusal: If one owner wants to sell, they must offer their share to the other co-owner first before going to a third party.
- Buyout Formula: How will the property be valued if one wants to buy the other out? Agreeing on using a certified market valuer prevents pricing wars later.
Divorce and Property
In a divorce settlement, the property usually has to be sold to split the proceeds, or one spouse buys out the other’s share.
- The Loan Trap: Even if the court grants the property to one spouse, the bank still considers both liable for the loan until it is refinanced or closed. You must ensure the exiting spouse’s name is formally removed from the loan records by the bank.
Inheritance, Succession & Nomination Rules
Buying luxury apartments is about building generational wealth. Ensuring that wealth passes to the right person requires clarity on succession.
Nominee vs. Legal Heir
This is a common misconception in India.
- Nominee: A nominee (e.g., in a cooperative society) is merely a trustee or caretaker of the property upon the owner’s death. They do not automatically become the owner.
- Legal Heir: The actual ownership passes to legal heirs as per the Will or personal succession laws.
The Importance of a Will
In “Tenancy-in-Common,” if a co-owner dies without a Will (intestate), their share gets distributed among all Class I heirs (spouse, children, and mother). This can complicate matters if the surviving co-owner (e.g., a brother) suddenly finds himself owning the house alongside his deceased brother’s wife and children.
- Solution: Always execute a Will clarifying who inherits your share of the joint property.
Why Location Matters: Choosing the Property Together
When buying jointly, the quality of the property matters as much as the legal structure. Check the location, approvals and total cost together before you commit.
What to check together
- Commute: test each co-owner’s commute at peak hours.
- Approvals and title: RERA registration, approvals and an independent legal opinion.
- Affordability: agree the EMI split and the maintenance share in writing.
Smart Ownership for a Secure Future
Joint home ownership is a powerful tool to fast-track your entry into the premium real estate market. It allows you to buy bigger, save more tax, and build a stronger asset base. However, it binds you legally and financially to another person.
The key to a successful joint purchase lies in transparency: clearly defined shares in the sale deed, a mutual understanding of financial contributions, and a rock-solid succession plan.
Ready to Make Your Joint Investment? Explore Auro Realty’s premium portfolio. Whether you are looking for investment-grade luxury apartments or a family home in Kondapur, our legal and sales experts can guide you through a seamless joint ownership process.
Sources & Legal Disclaimer
Legal provisions referenced in this guide are based on the Transfer of Property Act, 1882, Indian Registration Act, 1908, and Income Tax Act, 1961, as well as RERA Telangana guidelines (rera.telangana.gov.in). Registration procedures follow IGRS Telangana protocols (registration.telangana.gov.in).
Disclaimer: This article provides general legal and tax information for educational purposes. It does not constitute legal or tax advice. Please consult a qualified advocate or Chartered Accountant for guidance specific to your situation.
Tax note: the limits above are the old tax regime limits for FY 2025-26 and apply to co-owners who are also co-borrowers and pay their share. From 1 April 2026 the Income Tax Act, 2025 applies and section numbers may differ, so check the current provisions or ask a chartered accountant. This guide is general information, not tax advice.
See also: How to Buy Your First Apartment in Hyderabad.
Ready to start your search? Read the Telangana property registration process and how to verify RERA approval, then view Auro Realty’s residential projects.
For a project example in HITEC City, see Kohinoor for current details.
Frequently Asked Questions
What are the legal implications of joint home ownership in Hyderabad?
Joint home ownership in Hyderabad involves shared property rights, and all co-owners must be listed on the sale deed. Each owner has equal right to use and occupy the property unless otherwise agreed in a legal contract.
What are the tax benefits of joint home ownership in India?
Joint owners who are also co-borrowers can each claim individual tax deductions on home loan interest under Section 24(b) and principal repayment under Section 80C, effectively doubling the available tax benefits.
Can joint property owners sell their share independently in Hyderabad?
A joint owner can sell their undivided share of a property, but they cannot sell the specific portion without the consent of other co-owners. It is advisable to have a clear partition deed or joint ownership agreement.